Manufactured Home Loan: What You Need to Know
Manufactured home loans are easier to fund than you might think. We've been helping our clients with theirmanufactured home loanssince 2012.
We're not sure why it scares so many other lenders, when to be honest, there are just a couple of small detours that are required to fund manufactured home loans. Breeze Funding offers specialized financing options for certain manufactured homes that do not have a permanent chassis. Homes supported by piers, tie-downs, or other anchoring systems may also qualify, depending on the construction, foundation certification, and applicable loan program. Being tied down does not, by itself, establish whether a home has a qualifying permanent foundation. In some cases, an engineer can assess the existing support system, specify additional tie-downs, anchoring, or other foundation improvements, and certify the completed work as meeting the permanent-foundation requirements of the applicable loan program. Breeze Funding has helped borrowers pursue this path when the required work and certification can be completed.
What Is a Manufactured Home?
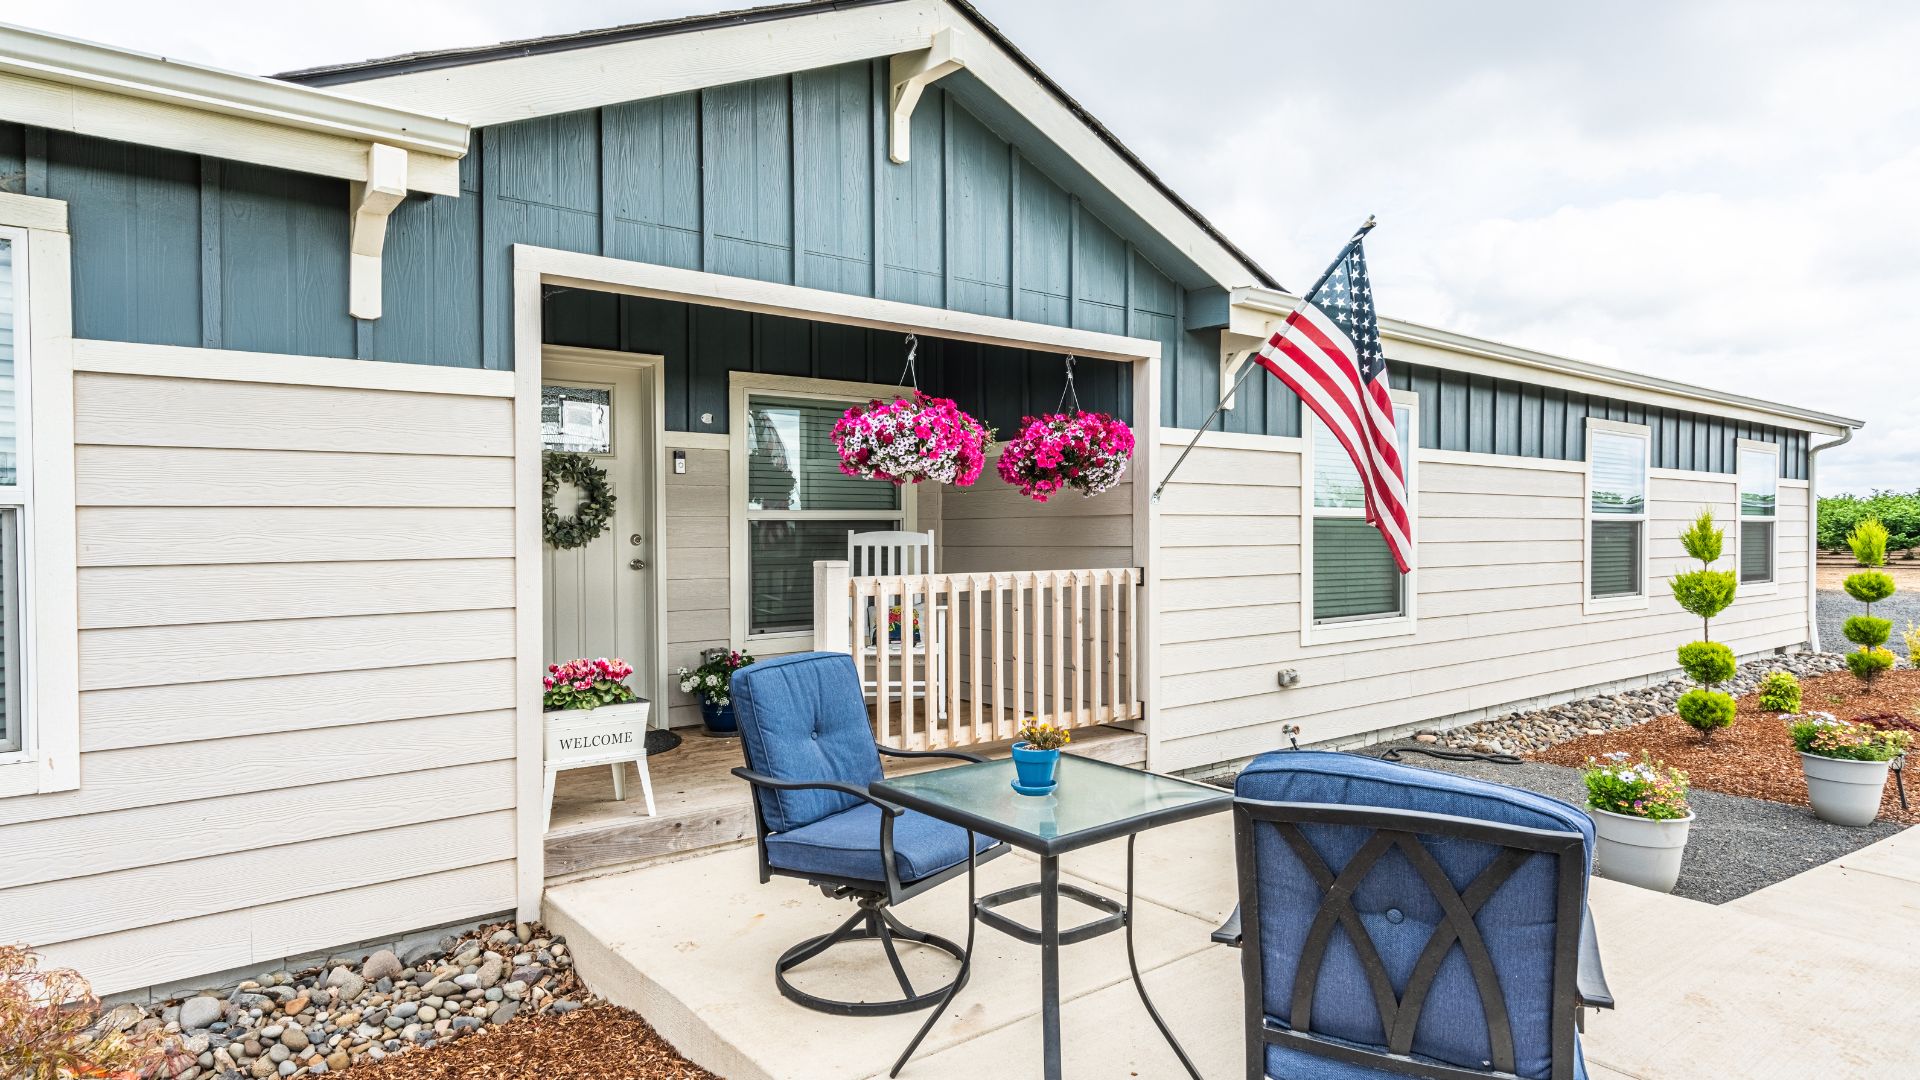
A manufactured home is a type of home that is built inside a factory and then shipped in one to 3 large sections to the home site. It is different than most houses that are known as "stick built" that are built onsite, piece by piece. New manufactured homes are often certified by federal rather than state housing authorities.
Manufactured homes typically have a steel chassis as part of their construction, while the foundation is the system that supports and anchors the home on its site. Chassis and foundation requirements are different and vary by loan program. Manufactured homes are generally classified by size as a single-wide manufactured home, double-wide manufactured home, or triple-wide manufactured home.
What are the requirements for a Manufactured Home Loan?
A manufactured home loan is very similar to a regular home loan, except for a few differences. For one thing, most manufactured homes that can be financed were built after 1976 as this is when the office of Housing and Urban Development (HUD) began issuing building standards for manufactured homes. In many cases, borrowers will need to produce a recent engineering certification to document that the manufactured home in its current condition conforms with federal requirements.
Additionally, appraisals for manufactured homes are usually more expensive than standard home appraisals because appraisers who evaluate manufactured homes are required to attain additional certifications.
What are the general requirements for a Manufactured Home Loan?
Requirements for manufactured home loans vary, but there are some common standards including:
- The manufactured home must have been built after 1976
- The manufactured home should not have been moved to a different location once it was placed on site
- The manufactured home must have its title converted to reflect as real property
- The manufactured home's tags should be accessible to the appraiser (either on the outside or in the kitchen cupboard)
- The manufactured home should not be on leased land unless the lease runs longer than the term of the loan
What to do if your Manufactured home doesn't meet the standards above?
Call us:855-346-7283
Breeze Funding has been proudly helping with financing on manufactured homes since 2012. Sometimes all it takes is an experienced team that knows how to help you get your manufactured home loan funded. We regularly help our clients with attaining IBTS tag reports, engineering certifications, and offer additionalmanufactured loan productsif FHA, VA, Fannie Mae, or Freddie Mac loans are not appropriate in your situation.
Two Ways We May Be Able to Help
A manufactured home that does not initially meet standard lending requirements may still have financing options. Breeze Funding can evaluate two possible paths:
- Specialized manufactured-home financing: Some programs may finance eligible homes that do not meet conventional chassis or foundation requirements, subject to the specific program's guidelines.
- Engineer-directed foundation improvements: An engineer may be able to evaluate the home and specify tie-downs, anchors, or other improvements. Once the work is completed and appropriately certified, the resulting system may qualify as a permanent foundation for the applicable loan program.
Tie-downs alone are not automatically a qualifying permanent foundation. The engineering design, completed installation, certifications, and lender requirements all matter. We can help review which route makes sense for your property.
Common Questions About Manufactured Home Loans
- Can I get a cash out loan on a manufactured home rental I own?YES
- Can I get a VA loan on a manufactured home?YES
- Can I get an FHA loan on a manufactured home?YES
- Can I get a manufactured home loan if my manufactured home is in a Condo Association?YES
- Can I get a manufactured home loan if my credit is bruised?YES
- Are there loans for manufactured homes without a permanent chassis?YES, for eligible properties under certain specialized programs.
- Can I get an FHA streamline loan on a manufactured home?YES
- Can I get a VA IRRRL loan on a manufactured home?YES